

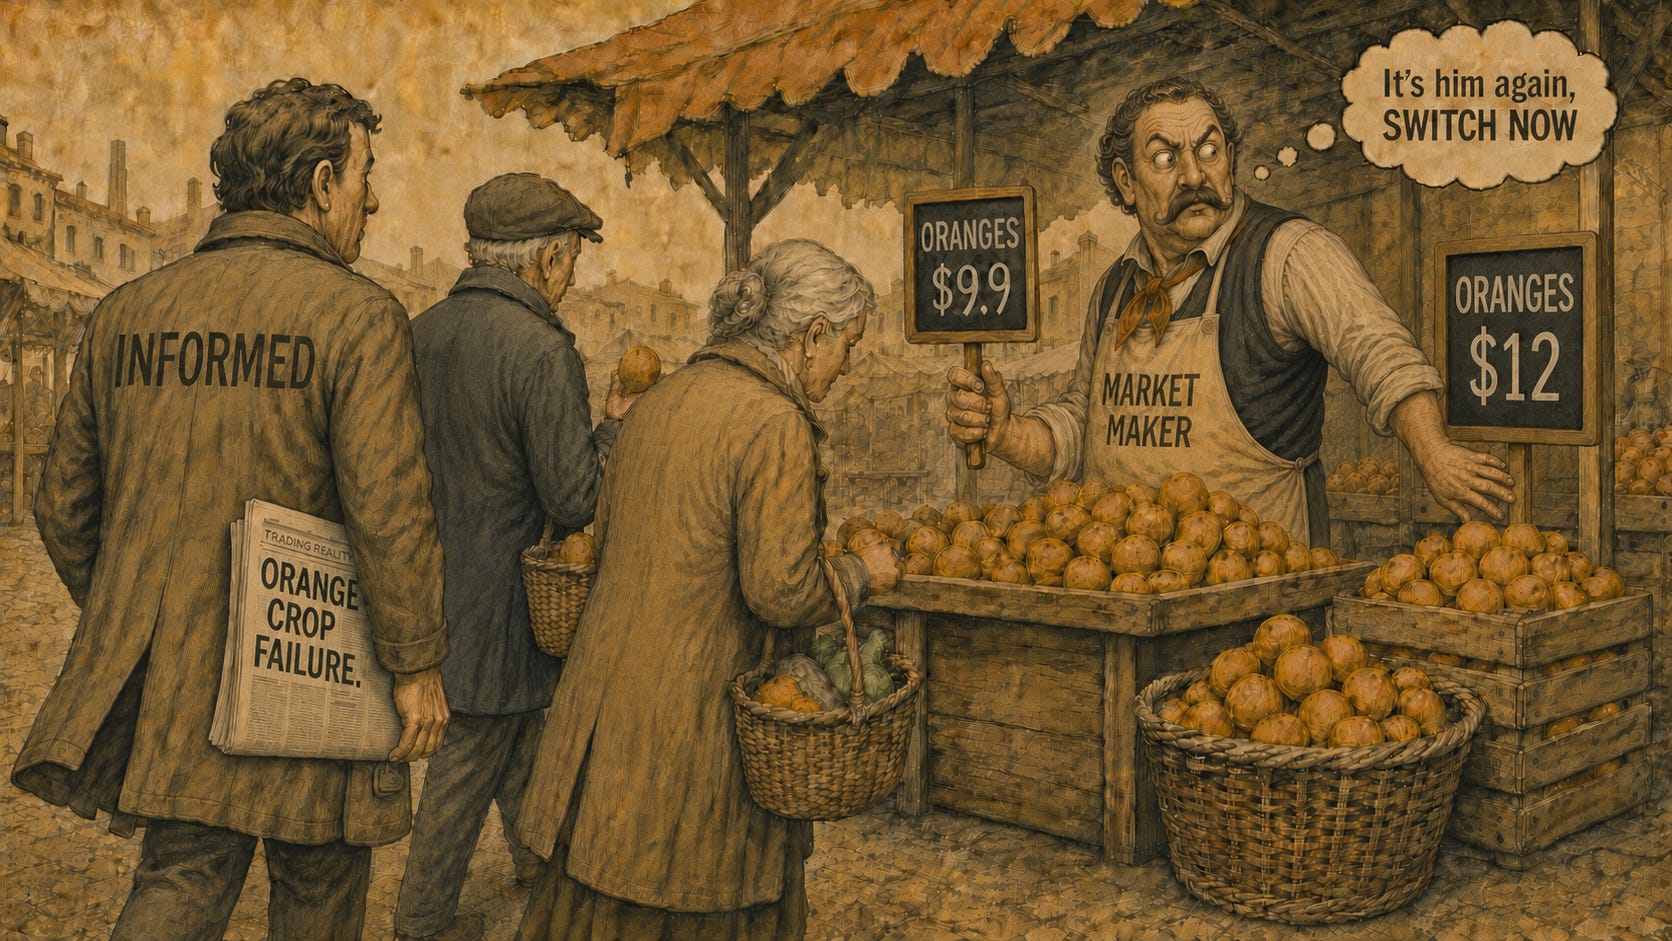
If you want to make it in trading — and in building trading systems in particular — the most important concepts to understand are not trends and reversals, not breakouts and fakeouts, not regime detection and volatility clustering. The single most important set of concepts revolves around market participant behavior. But not in the naive sense of trading psychology, which is a form of hype that circulates mostly in non-professional circles. What matters is the structural makeup of market participants, and how that structure changes.
There is little value in obsessing about the fear and resulting actions a retail trader goes through upon detecting a pattern, when retail traders make up a minuscule percentage of the market anyway — and even that portion is diluted by stacking on top of some larger player who has already purchased the flow from the Robinhoods of this world.
In the last piece I closed with the question of why good signals have a front-loaded shape. The answer starts with who is on the other side of those signals — and that is where this piece picks up.
Let’s focus on two participant categories whose implications cannot be overstated: they will determine how you trade, how much you trade, what you can trade, and when you trade. Many readers will be familiar with informed and uninformed traders. Few realize that informedness only makes sense relative to a third participant — the market maker. So that is where we have to start.
Market making, in practice
In the early 2000s I was CTO/COO of an HFT shop that did what we called 5-5 for years (a tongue-in-cheek nod to hedge fund fee structure). With a headcount of just five people, we matched 5% of Nasdaq OTC volume. As part of the incessant pursuit to chisel away unit costs, we had a seat at the exchange, were a registered market maker, and were a self-clearing broker-dealer.
Without getting into the distinction between designated and primary status, registered market makers are required to quote two-sided continuously during regular trading hours, within a defined band of the National Best Bid and Offer. The point is that being more than just an Electronic Liquidity Provider — quoting voluntarily, withdrawing when unprofitable — came with obligations, and those obligations came with allowances. The rules differ slightly for options, but the concept is the same.
One point worth emphasizing because it tends to be missed: a market maker is not obligated to always sit at the inside bid and ask. They are required to quote a certain percentage of the time and within a defined band of the prevailing best bid/ask. They are designated as providing liquidity, which is itself considered a service. That liquidity is not a guarantee, and market makers compete with all other participants for profit. They are neither the villain of the market story nor a benevolent provider of public good — just another competing participant.
So why spend this much time on market makers if what we want to focus on is informed and uninformed traders? Because informedness is defined relative to the market maker. Not as a pure concept. As a structural relation. And as I will show, the distinction between informed and uninformed is not an incidental property of who happens to be in the market. It is not a “designation” of who is smart and who isn’t. It is a structural and unavoidable feature of how markets operate.
A flash history of informedness
The distinction between informed and uninformed traders has been discussed since at least 1971, when Bagehot — the pseudonymous Jack Treynor — framed market making as a contest between liquidity providers and traders with superior information. The formal academic framework arrived with Kyle (1985) and Glosten-Milgrom (1985). What this body of work established is that the distinction is structural, not behavioral. It is integral to how markets operate, not an incidental fact about who happens to be trading on a given day.
Your intuition that a big institution’s block trade, or a super-pod order from the Millenniums and Citadels of the world, would be termed informed — while a retail order is uninformed — is not really the correct distinction according to this framing. And yet, this remains a valid way to think about informedness. At least as a starting point. Size enters the story too: Kyle’s 1985 model is built on the idea that informed traders strategically choose how aggressively to trade because their order size and timing leak information to the market. The bigger the trade, the more the maker can infer, the more the price moves before the trade completes. Size is not what defines informedness, but it is one of the signatures by which informedness gets detected. At our HFT shop we ran algorithms tuned specifically to detect block trades hiding behind VWAP/TWAP slicing — the size signal worked in both directions.
The Uninformed come to the rescue
The above intuition breaks down when you push it further, however. What if all the retail-like flow disappeared, one might ask — and you can argue this is already partially the case given the retail order flow business operating upstream of public venues. Would the markets become more efficient? Would informed-on-informed be the new reality?
No, and the reason is structural. Uninformed flow isn't just the contrast that defines informedness — it's what makes the market work. The literature is precise on this: Black (1986) called noise traders necessary, and the no-trade theorem (Milgrom and Stokey, 1982) shows why. If everyone were rational and informed, the fact that someone wants to trade with you would tell you they think they have an edge — so you should refuse. Markets seize up. Liquidity disappears. I saw this at the HFT in the small: we refused to trade with players whose cancel/replace patterns suggested they were reading the same signals we were. The theorem isn't abstract — it's how a desk actually operates when it suspects the other side knows what it knows.
Noise traders break the deadlock. Their flow has no information in it, which gives informed traders something to trade against and lets prices catch up to reality. The uninformed lose on average. That’s the cost of having a market at all. It is this informational asymmetry that makes the price tick.
Definition. Please.
It is dead simple. If the Market Maker loses when trading against you, you are informed. If they make money, you are uninformed. Don't try to beat the market. Beat the Market Maker first.
He who Makes the vocabulary
The language has evolved. From 1971 to today the terms have drifted: uninformed became noise trader, informed became toxic flow. Notice how the names have become pejorative for both groups. Uninformed flow used to be a structural necessity; now it's noise. Informed flow used to be the trader earning a return on their information; now it's toxic.
The vocabulary tells you whose seat at the table got the loudest voice. That seat belongs to the third participant we have been circling: the Market Maker.
Some readers will recognize toxic order flow from a different marketplace than this piece centers on: CFDs. Colloquially called FX. Liquidity providers in that business throw the term around a lot, especially when they want to upcharge or restrict access. This is no coincidence. Informed, uninformed traders and market makers are not exclusive to centralized markets. They are emergent features of any market where someone quotes both sides. The vocabulary ports because the structure does.
Why this matters for trading systems
Some of the cleanest, most reliable strategies I have worked on were ones we eventually traced back to a specific class of participants doing a specific thing. The strategies we couldn't trace? Those went away first. Half-life detection is great, but it's only a "half-solution".
Every trading system makes assumptions about participant mix, whether the developer knows it or not. The strategy that worked in backtest assumed a certain composition of flow. The execution model that produced a clean equity curve assumed a certain receptivity from the makers on the other side. When the mix changes — and it does, regularly — the assumptions degrade. Quietly.
You can build trading systems without thinking this way. Plenty of people do. But if you arrive at a persistent edge without ever asking whose behavior this is exploiting, you have most likely found a participant-structural pattern without knowing it. Which means when it goes away — and it will — you won't know why.
Adverse selection is one of the mechanisms that turns participant structure into the actual cost of trading. And it defines the spread. Now we can explore it substantively, and that is what my next piece will do. And with this we add very important concepts to our toolkit — ones that will survive any trend, strategy, and possibly even you and me.
References
Bagehot, W. [Treynor, J.] (1971). The Only Game in Town. Financial Analysts Journal, 27(2), 12-14.
Milgrom, P., & Stokey, N. (1982). Information, Trade and Common Knowledge. Journal of Economic Theory, 26(1), 17-27.
Black, F. (1986). Noise. Journal of Finance, 41(3), 528-543.
Further reading
De Long, J. B., Shleifer, A., Summers, L. H., & Waldmann, R. J. (1990). Noise Trader Risk in Financial Markets. Journal of Political Economy, 98(4), 703-738.
Easley, D., Kiefer, N. M., O’Hara, M., & Paperman, J. B. (1996). Liquidity, Information, and Infrequently Traded Stocks.Journal of Finance, 51(4), 1405-1436.
Easley, D., López de Prado, M., & O’Hara, M. (2012). Flow Toxicity and Liquidity in a High-Frequency World. Review of Financial Studies, 25(5), 1457-1493.
Thank you, Tibor, at India NSE equity and index derivatives operate as a pure electronic order-driven continuous auction (limit order book) without formal continuous quoting obligations by market makers. Being a Trader, my options algo checks stale quotes on stock options at market opening, it regularly finds PE/CE spreads blown >150%, sometimes no bid-ask quotes for first 90 seconds. The algo checks whether the book is tradable: quotes are fresh, bid-ask spread within limits defined, book depth is available else it dynamically hedges (if outside delta band) via futures till the spread, quotes and liquidity appears. My current operational monitoring is at 500 milli seconds.
Given your background as MM, any good whitepapers, pointers for me to make my execution even more robust. What else can be done for better operations? Your guidance and help is appreciated.
https://themarketjourney.substack.com/p/market-makers-in-options-and-futures
Some time ago, I conducted an analysis of futures and options using OCC data, specifically aiming to understand the distinct role of market makers for both financial instruments.
From your perspective, could you confirm my interpretation or not?
Thank you very much.